NRB Allows Nepali Companies to Invest Abroad!
Khatapana
December 26, 2025 11 min read
 Reviewed by Kailash Panday, Chartered Accountant & Corporate Lawyer
Planning to set up a branch office abroad? This guide explains what NRB allows, eligibility rules, approvals, limits, and compliance for Nepali IT companies.
Until recently, the idea of a Nepali company setting up a branch office abroad sounded almost rebellious. Not illegal, just impractical. Between foreign exchange controls, approval layers, and the general fear of capital flight, Nepal’s regulatory system was designed to keep money in, not help companies expand out.
That changed when Nepal Rastra Bank (NRB) amended the Foreign Investment and Foreign Loan Management Bylaws, 2078, and aligned them with the Foreign Investment and Technology Transfer Act, 2075 (FITTA).
If you’re an IT company exporting services, earning foreign currency, and paying taxes in Nepal, the system will now allow you to expand your existence abroad.
But don’t mistake this for a “go incorporate anywhere you like, however you like” policy.
What NRB has created is a controlled exit lane, one that allows outward expansion only if it is backed by real exports, real earnings, and real compliance. And that’s where most confusion starts. Because founders hear “allowed to set up a branch office abroad” and assume freedom. What the law actually offers is permission, but with strict structure, ceilings, and supervision.
To understand how far you can go, the first question you need to answer is not where you want to expand. It’s whether you’re even allowed to.
The Legal Foundation: Who Allows What (And Who Controls the Money)
A common misconception is that one NRB circular suddenly made foreign expansion legal.
That’s not how this framework works.
The permission for Nepali IT companies to set up a presence abroad exists only because three legal layers operate together, each controlling a different part of the process:
- One law allows the concept of a foreign presence
- One law confirms what kind of business you are
- NRB decides whether money is allowed to leave Nepal
Understanding this split is critical, because most confusion, and bad advice, comes from mixing these roles up.
FITTA, 2075: Permission to Exist Abroad
The starting point is Section 7A(3) of the Foreign Investment and Technology Transfer Act, 2075 (FITTA).
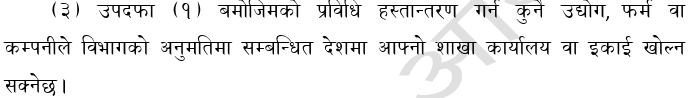
This provision allows a Nepali company to establish a branch or unit abroad for technology transfer purposes, with prior approval from the Department of Industry (DoI).
One important thing to be noted is: DoI approval is required only when you are setting up a new branch or unit abroad.
If you are investing in an existing foreign entity, you do not need approval from DoI
Basically, FITTA answers only one question: Are you legally allowed to have a foreign presence at all?
Industrial Enterprise Act, 2076: Identity Confirmation
Whether you can use this framework also depends on how your company is officially classified.
Banks and regulators rely on your classification under the Industrial Enterprise Act, 2076, not your marketing description. If your company is not recorded as an IT industry in government systems, problems might surface later, usually at the foreign exchange stage.
Nepal Rastra Bank: Control Over Foreign Exchange
Finally, there’s NRB.
FITTA may allow you to go abroad, the Industrial Enterprise Act may confirm who you are, but NRB controls whether any foreign exchange is released at all.
Through the Foreign Investment and Foreign Loan Management Bylaws, 2078 and the NRB Unified Circular 2081, NRB decides how much money can leave Nepal, for what purpose, through which bank, and with what reporting and repatriation obligations
With this foundation clear, the next question is: Who actually qualifies to use this framework, and who doesn’t?
That’s where we turn next.
Who Is Actually Eligible (And Who Should Stop Right Here)
Let’s get this out of the way early: this outward investment facility is not for all Nepali companies. It is not even for all tech startups.
As previously mentioned, only companies classified as an “Information Technology Industry” under the Industrial Enterprise Act, 2076 are eligible. Which means, when you ask for foreign exchange approval, NRB doesn’t care what you call yourself on LinkedIn, it only cares about how the law classifies you.
In practical terms, this includes companies engaged in any of the following:
- Software development
- IT-enabled services (BPO/KPO)
- Cloud computing and data centers
- Web services and digital platforms
- Digital data processing, migration, and design services
- IT-based outsourcing, technical, and management services
This scope comes directly from Section 2(f) of FITTA, 2075, which defines technology transfer broadly enough to cover modern digital exports.
But classification alone is not enough.
The 3-Year Foreign Currency Test
NRB’s outward investment window is built on one non-negotiable condition: You must have earned foreign currency from IT or service exports for at least the preceding three fiscal years.
Not projected revenue, not signed contracts, not invoices sitting unpaid.
Actual foreign currency earnings, reflected in your accounts, verified by banks AND audited.
Basically, NRB only wants to back proven exporters. So if you’re not there yet, this provision might not be the right fit for you.
What About Revenue From India?
This is where things get interesting, and often misunderstood.
If your IT exports are to India, your earnings may be in INR rather than USD or other convertible currencies. NRB allows this, but it expects clear documentation, including the following:
- NPR account details where INR earnings are credited
- A bank-issued INR earnings certificate confirming export receipts
In other words, India revenue counts, but only if it is cleanly traceable through the banking system.
If you don’t meet these eligibility conditions, no amount of structuring or legal drafting will change that.
If you do meet them, the next question is: Which route are you supposed to use for sending money to your branch office abroad?
Two Very Different Routes to Invest Abroad (Don’t Mix Them Up)
NRB has deliberately created two distinct outward investment routes, each meant for a different scale and purpose of expansion. Confusing them leads to wrong documents, wrong expectations, and wasted months.
Let’s separate them clearly.
3.1 The IT-Specific “10% Facility” Route
As mentioned in Section 5(A) of the NRB’s Unified Circular 2081 on foreign exchange transactions, IT and service-exporting companies are allowed to access foreign exchange through their commercial banks without needing separate NRB approval for specific purposes.
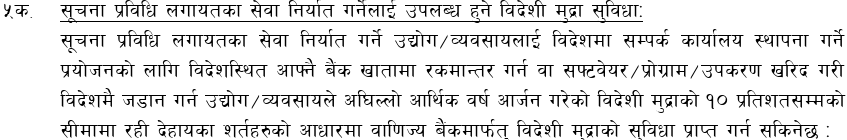
But the freedom comes with tight numerical limits.
The Two Linked Limits You Must Respect
Under this route, the amount you can use must satisfy both conditions:
- Up to 10% of your foreign currency earnings from the previous fiscal year, and
- Within 20% of the taxable income shown in your tax clearance certificate
Whichever is lower becomes your outward investment ceiling.
This ensures two things. For one, you can’t drain foreign currency just because revenue looks high. And you can’t bypass tax discipline to fund overseas expansion
More importantly, according to section 5A(3) of the NRB’s Unified Circular 2081 on foreign exchange transactions, there is no separate NRB approval just to open a foreign bank account under this route.
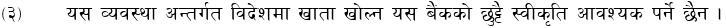
The entire process flows through your commercial bank, which in turn reports to NRB.
This makes the 10% route efficient, but quite limited in terms of the amount you are allowed to invest abroad.
Which brings us to the second route.
3.2 The Full NRB Approval Route
(Slower, heavier, unavoidable for bigger bets)
The moment you want to invest beyond the 10% / 20% limits, or make larger equity investments in a foreign entity, the simplified facility no longer applies to you.
At that point, you must obtain explicit NRB approval, in addition to consent from the Department of Industry (DoI) under Section 7A(3) of FITTA, 2075.
This route involves deeper scrutiny of capital structure, stronger governance and integrity checks, and clear justification for the investment size
This is also where investment ceilings, paid-up capital limits, and USD caps start to matter, which is exactly where we’ll go next.
By now, three things should be clear:
- Not every IT company qualifies
- Not every qualified company gets unlimited freedom
- The route you choose determines everything that follows
Let’s now zoom into the hard ceilings that apply regardless of ambition, and why even NRB approvals cannot override them.
The Hard Ceilings You Cannot Cross (Even With Approval)
Regardless of whether you’re using the 10% facility or going through full NRB approval, there are ceilings you simply cannot cross, no matter how strong your global your ambition feels.
The Paid-Up Capital Ceiling (Paper Profits Don’t Count)
The first ceiling is deceptively simple: Your total outward investment cannot exceed your paid-up capital.
Paid-up capital is the anchor because NRB is looking at risk absorption, not growth stories. If your foreign venture fails, the regulator wants to know there is enough committed capital in Nepal to absorb the loss without destabilizing the system.
This is where many otherwise profitable companies hit a wall, especially bootstrapped IT firms that never bothered to increase paid-up capital because “it wasn’t needed.”
For NRB, it suddenly is.
The Two-Layer Foreign Exchange Cap
Then comes the second, and more technical set of limits.
Even if your paid-up capital is high, your outward investment is further capped at the lower of:
- 50% of the average foreign currency earnings from IT exports over the preceding three fiscal years, or
- USD 1 million (or equivalent in another convertible currency)
This structure matters. NRB is deliberately tying outward expansion to export consistency, not one lucky year.
Let’s make this real.
Example 1: Small but Profitable IT Firm
- Average FX earnings (last 3 years): USD 400,000
- 50% of that: USD 200,000
Even if the company’s paid-up capital is NPR 10 crore, USD 200,000 becomes the real ceiling. Not because NRB doubts your capability, but because it wants outward investment to remain proportional to sustained inflows.
Example 2: High-Revenue, Low-Capital Startup
- Average FX earnings: USD 3 million
- 50% = USD 1.5 million
- Hard stop applies: USD 1 million
Even here, NRB draws a line. The cap exists to prevent large, sudden capital movements that could quietly turn into capital flight.
Why NRB Designed It This Way
This isn’t bureaucratic paranoia. It’s macro-prudence.
Nepal runs a structurally sensitive foreign exchange regime, and NRB’s job is to make sure outward expansion does not quietly become wealth parking abroad, promoter exit strategies, or unmonitored offshore accumulation.
So the rule is blunt but fair: Grow globally, but only as fast as you earn globally.
Once these numbers make sense, the rest of the journey becomes procedural.
The Approval Flow: Who You Approach, In What Order
NRB has not designed this as a walk-in approval system. The flow is deliberate, layered, and role-specific.
A. Internal Company Preparation (Where It Really Starts)
Before any bank, any department, or any form, everything starts inside your boardroom.
And no, one generic board resolution won’t cut it.
NRB expects two distinct board resolutions, each serving a different legal purpose:
- A resolution requesting access to the foreign exchange facility / outward investment, specifying the purpose (branch, liaison office, investment, etc.), amount, and jurisdiction
- A separate resolution accepting responsibility for full compliance with foreign exchange laws, reporting obligations, and repatriation requirements
These are not interchangeable because one authorizes action, while the other assigns accountability.
Alongside this, shareholders and directors come under heavy scrutiny. NRB wants to see who actually controls the company, not just on paper, but in practice.
This is also where compliance declarations begin. Often underestimated, often rushed, and frequently sent back for clarification.
B. Application Submission (Why You Don’t Walk into NRB Directly)
Under both the simplified facility and the approval route, your commercial bank is the gatekeeper. The application flows through the bank, which reviews documents, assesses eligibility, ensures completeness, and submits reports to NRB
NRB relies on banks as its first line of filtering. If the bank is unconvinced, the file doesn’t move.
The Department of Industry (DoI) comes into play specifically under Section 7A(3) of FITTA, 2075, where outward establishment for technology transfer purposes requires its prior approval, especially for branch or unit setups.
Founders who treat NRB and DoI as two unrelated steps usually learn, painfully, that the system does not.
C. NRB Decision Timeline
Once a complete application reaches NRB, the expectation is a decision within 15 working days.
But “decision” does not always mean approval.
In practice, it can be any of the following:
- Approval, allowing the bank to release foreign exchange
- Clarification requests, pausing the clock
- Rejection, usually due to structural or compliance gaps
Communication typically happens through the bank, not directly with the company. So if there’s unusual silence after application submission, understand that something is missing. Which brings us to the most operationally critical section of all.
The Complete Document Checklist You’ll Need
NRB’s documentation expectations are exhaustive, but not arbitrary. Each document answers a specific risk question.
A. Core Company Documents
These establish legal existence and financial credibility:
- Company Registration Certificate and PAN
- Memorandum and Articles of Association
- Latest audited financial statements
- Tax clearance or filing certificate
- Updated shareholder and director records from the Office of the Company Registrar
B. Financial & Banking Declarations
This is where foreign exchange discipline shows:
- Proof of FX earnings from IT/service exports
- For India earnings: NPR account details and bank-issued INR earnings certificate
- Convertible foreign currency account details
- Self-declaration confirming no overdue loans or defaults with Nepali banks or financial institutions
C. Governance, Integrity & Fit-and-Proper Declarations
This section feels heavy because it is.
NRB requires self-declarations from:
- Shareholders
- Board members
- CEO
- Company Secretary
- Beneficial owners
Each declaration confirms, among other things:
- Nepali citizenship and minimum age
- Sound mental health
- No insolvency or forced settlements
- No financial blacklist in the last three years
- Full tax compliance
- No recent convictions for serious crimes, corruption, money laundering, or terrorist financing
D. Foreign Entity-Specific Documents
Requirements differ based on whether you are establishing a branch or liaison office, or investing in an existing foreign entity
Documents may include:
- Foreign registration certificates
- Latest audited financial statements (or unaudited statements with proof of audit exemption, where applicable)
- Notarized beneficial ownership disclosures (with limited exceptions for listed entities.
NRB’s concern here is simple: Who controls the foreign vehicle, and can it be monitored?
At this point, approval may feel close. But in NRB’s world, approval is not the finish line.
It is permission to be watched.
Next, we’ll look at what happens after approval (reporting, repatriation, and the consequences of getting casual once the money has already moved.)
Post-Approval Obligations (Where Compliance Actually Begins)
This is precisely the moment NRB starts paying closer attention, because for the regulator, this is just the beginning.
Ongoing Reporting Through Schedule 7.8
Every outward investment or foreign office funded under this regime comes with a recurring reporting obligation under Schedule 7.8 of the NRB framework.
This schedule captures the details of the foreign investment or branch, amount of foreign exchange utilized, purpose-wise deployment, and changes in ownership, structure, or control
It is not optional, and it is not annual-only.
The 7-Day Rule (This Is Where People Slip)
Both the bank and the company have reporting obligations, and NRB has made the timelines intentionally tight.
Commercial banks must submit transaction details to NRB within 7 days after the end of each month
Companies must submit utilisation and reporting details in the prescribed format within the same 7-day window
This is not ceremonial reporting. NRB cross-checks bank submissions against company disclosures, and mismatches will raise flags.
Many founders make the mistake of assuming that reporting can wait until “things settle.” NRB does not share that patience.
Annual Financial Submissions for Foreign Operations
Beyond monthly reporting, companies must submit Audited financial statements of the foreign branch or investment within six months of the end of the fiscal year.
If the foreign jurisdiction does not legally require audits, NRB allows Unaudited financial statements, provided you submit acceptable proof that audit is not mandatory in that jurisdiction.
This flexibility exists, but only if documented properly.
Repatriation of Income (What Counts, and How It Must Flow)
NRB’s outward investment permission is built on one expectation: Money earned abroad must come back through the formal banking system.
This includes profits from the foreign branch, service fees or reimbursements, and refunded or unused investment amounts
Repatriation must happen through recognised banking channels. Informal adjustments, netting arrangements, or “we’ll balance it later” logic is exactly what NRB is trying to prevent.
Consequences of Misuse
NRB does not need dramatic enforcement to be effective.
Misuse (or even casual non-compliance) can result in restrictions on future foreign exchange access, delays or denials in unrelated FX approvals, heightened scrutiny across banking relationships
Knowing the law is one thing. Surviving implementation is another.
A Practical Readiness Checklist (Founder Self-Audit)
Before you act, or re-act on any outward expansion plan, pause and run this internal audit.
Eligibility confirmed
- Classified as an IT industry under the Industrial Enterprise Act
- At least three years of verifiable foreign currency earnings
Are you setting up a new entity or investing in an existing entity?
- DOI approval required for setting up a new entity abroad
Route identified
- 10% IT facility via commercial bank, or
- Full NRB approval route (with DoI involvement)
Limits calculated conservatively
- Paid-up capital checked
- 50% of average FX earnings (last three years) computed
- USD 1 million hard stop respected
Documents pre-assembled
- Board resolutions (both of them)
- Financials, tax clearance, FX proofs
- Governance and self-declarations ready
Is the bank engaged early?
- Not after documents are “final”, but while structuring the application itself
If even one of these feels fuzzy, that’s your signal to slow down.
Final Thoughts
NRB has done something genuinely important here.
It has acknowledged that Nepali IT companies don’t need to stay local to remain loyal. It has created a legal path to expand globally without dismantling foreign exchange discipline.
But this framework is intentionally not liberal.
It enables operational expansion backed by real exports, branch offices that support service delivery, and controlled equity investments tied to performance
And it deliberately restricts capital flight masked as expansion, promoter-led offshore parking, and speculative outward bets disconnected from earnings
The biggest winners in this system will be the disciplined exporters, not loud ones.
If you approach global expansion with that mindset, this framework actually protects you, and not limit you.
Starting a business in Nepal?
Register your company online — name reservation, MOA/AOA, PAN/VAT and OCR filings, all in one place.


Related Blogs
Subscribe to our newsletter
Get latest news and updates directly to your email.