TDS Rates in Nepal 2083/84 with Revenue Codes (Table)
Khatapana
October 16, 2026 6 min read
 Reviewed by Kailash Panday, Chartered Accountant & Corporate Lawyer
TDS (tax deducted at source, अग्रिम कर कट्टी) is the tax a payer deducts when making certain payments and deposits with the Inland Revenue Department (IRD).
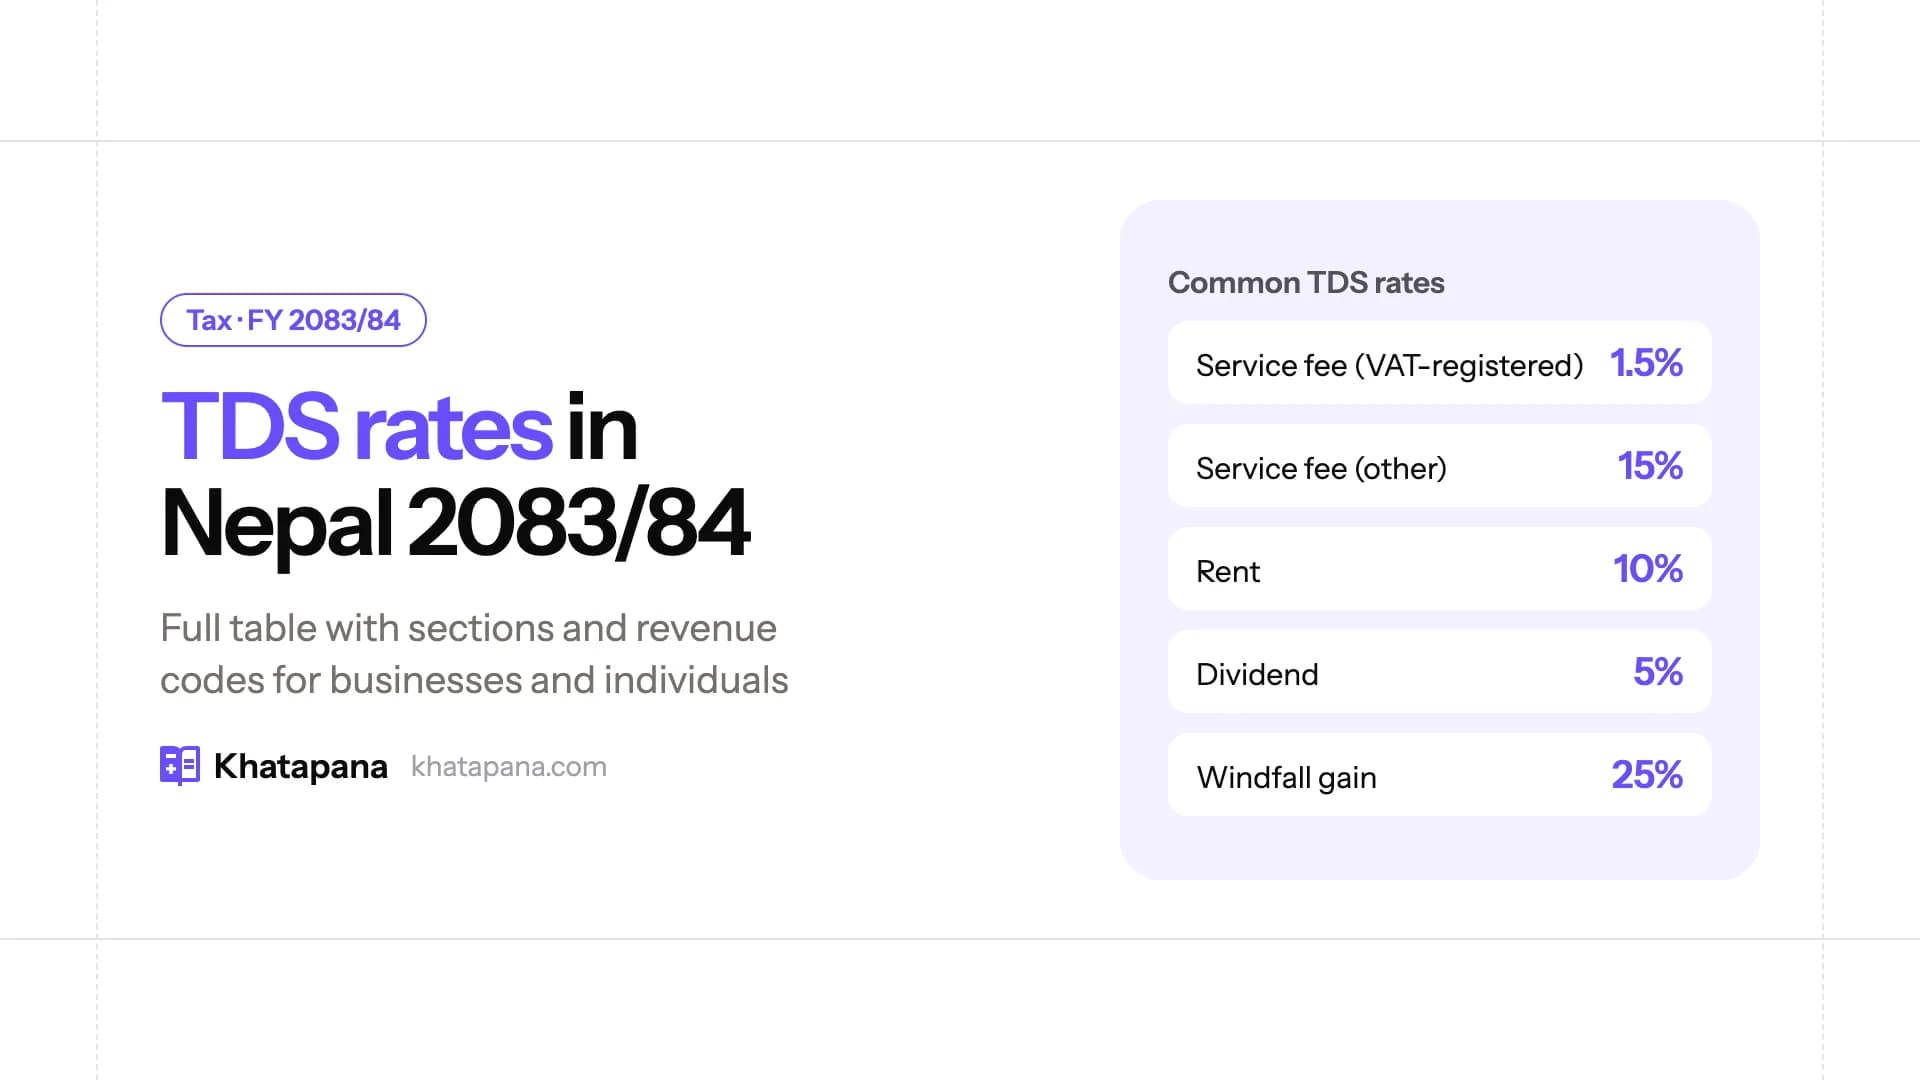
For FY 2083/84 the main rates are:
- 1.5% on service fees paid to VAT-registered persons and on contracts above Rs 50,000
- 15% on service fees, commissions and royalties paid to non-VAT persons
- 10% on rent paid by a business
- 5% on dividends
- 6% on interest paid by banks to individuals
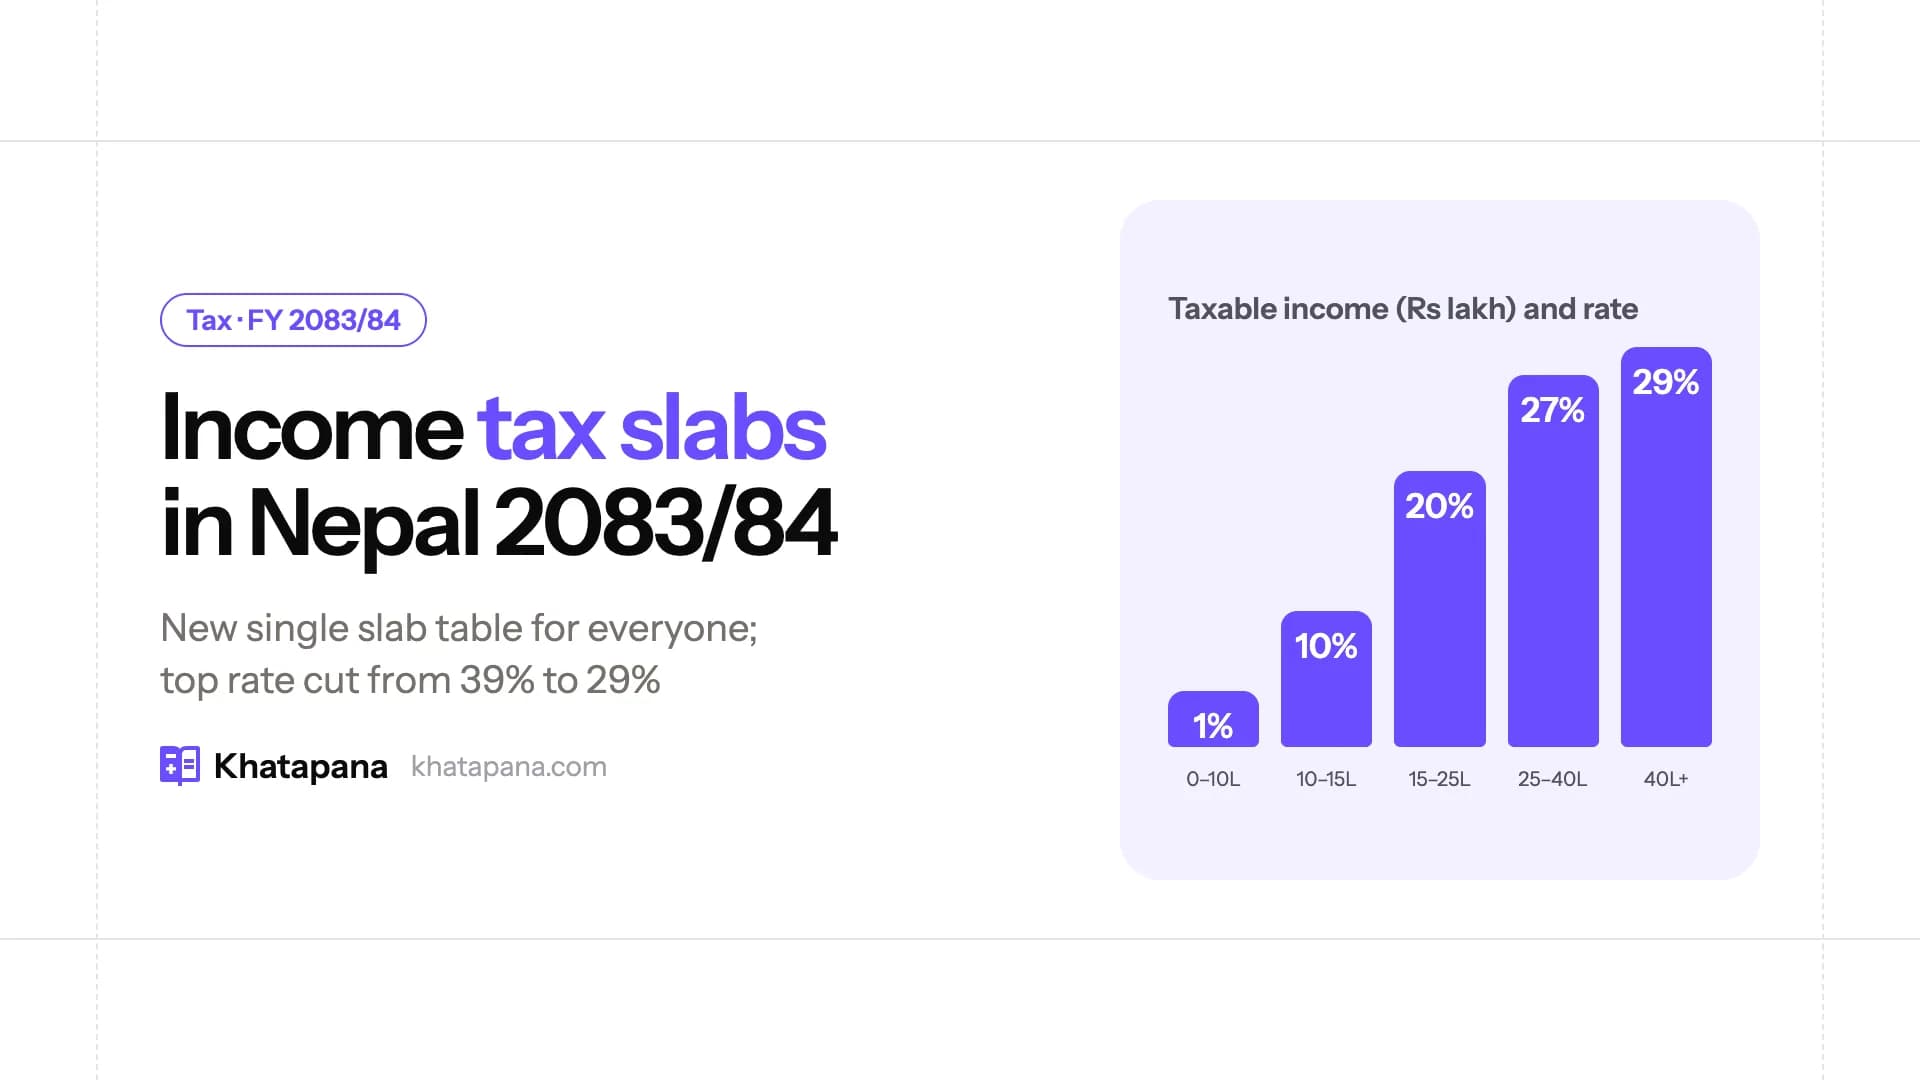
- salary slab rates on employment income
You must deposit the TDS and file the e-TDS return within 25 days after the end of each month.
Source: IRD notice "आयकर ऐन, २०५८ को दफा ८७, ८८, ८८क. र ८९ बमोजिम भुक्तानीमा अग्रिम कर कट्टी तथा दफा ९५क. बमोजिम अग्रिम कर असुली सम्बन्धी व्यवस्था (२०८३/०८४)". IRD publishes it as a PDF, so link to the IRD page for the "TDS rate pdf".
TDS rate in Nepal 2083/84 (full table)
Common business payments
| Payment | Section | TDS rate |
|---|---|---|
| Salary / employment income | 87(1) | Slab rates (see tax slab 2083/84) |
| Service fee to a VAT-registered resident service provider (or to a VAT-exempt resident entity) | 88(1)(4) | 1.5% |
| Service fee, commission, royalty, sales bonus, natural resource payment (Nepal source, other cases) | 88(1) | 15% |
| Contract or agreement payment above Rs 50,000 (resident) | 89(1) | 1.5% |
| Rent (Nepal source) paid by a resident person | 88(1)(5) | 10% |
| Vehicle rent paid to a VAT-registered vehicle-hire business | 88(1)(5)(ka) | 1.5% |
| Transport service / vehicle hire (non-VAT) | 88(1)(8) | 2.5% |
| Transport service / vehicle hire (VAT-registered) | 88(1)(8) | 1.5% |
| Meeting allowance, part-time teaching, question setting, answer-sheet checking | 88(1), 92(1)(ja) | 15% (final) |
| Royalty for literary articles or works to a resident | 88(1)(13) | 1.5% |
| Commission to an insurance agent (natural person) | 88(1)(14) | 20% (final) |
| Commission paid by a resident employment company to a non-resident | 88(1)(2) | 5% |
| Aircraft lease payment | 88(1)(3) | 10% |
| Satellite, bandwidth, optical fibre, telecom equipment or transmission line use | 88(1)(7) | 10% |
| Fees to a foreign school or university (registration, tuition, exam) | 88(1)(11) | 5% |
Investment and finance payments
| Payment | Section | TDS rate |
|---|---|---|
| Interest (Nepal source), general | 88(1) | 15% |
| Interest on deposits, debentures or government bonds paid by a bank, financial institution, cooperative or listed company to a natural person (not business-related) | 88(3) | 6% (final) |
| Dividend | 88(2)(ka) | 5% (final) |
| Investment insurance benefit | 88(2)(kha) | 5% |
| Benefit from an unapproved retirement fund | 88(2)(ga) | 5% |
| Retirement payment from Government or an approved fund, on the amount after deducting the higher of Rs 5 lakh or 50% | 88(1)(1) | 5% |
| Mutual fund distribution to a natural person / to others | 88(1)(6) | 5% / 15% |
| Interest paid by a bank to a life insurer on deposits | 88(1)(12) | 5% |
| Windfall gain (lottery, prize, gift…) | 88ka(1) | 25% |
| National or international awards up to Rs 5 lakh for contribution to literature, art, sport, science and similar fields | 88ka(2) | No TDS. 25% on the amount above Rs 5 lakh |
Advance tax collected (section 95ka)
| Payment | TDS rate |
|---|---|
| Gain on listed shares: resident individual, held more than 365 days | 7.5% |
| Gain on listed shares: resident individual, held 365 days or less | 10% |
| Gain on listed shares: resident entity / others | 10% / 25% |
| Gain on unlisted shares: resident individual / resident entity / others | 10% / 15% / 25% |
| Gain on land or house (individual): owned 5 years or more / less than 5 years | 7.5% / 10% |
| Land compulsorily acquired by the Government | 2.5% |
| Land or building sold by persons other than above (on sale value) | 1.5% |
| Commodity futures profit | 10% |
| Foreign-currency income of an individual not in business, for software/electronic services, personal consulting abroad, or social-media content | 5% (final) |
| Payment by an e-commerce operator to sellers on its platform | 1% |
| Payment by a ride-sharing operator to riders/drivers | 1% (final, new in 2083/84) |
| Foreign exchange for language/standardised test fees for students going abroad | 15% |
Payments to non-residents
| Payment | TDS rate |
|---|---|
| Contract payments to non-residents | 5% |
| Insurance premium to a non-resident insurer, or reinsurance commission | 1.5% |
| Other payments to non-residents | As notified by IRD in writing |
No TDS on:
- house rent received by an individual (natural person) for their own house. The local government collects rent tax instead.
- incentives given to consumers for paying by card, wallet or mobile banking
- payments by a natural person that are not related to running a business
- articles published in newspapers or magazines
- interest paid to resident banks and financial institutions
- interest between cooperatives
- exempt payments
- interchange fees paid to card-issuing banks
What changed from TDS rates 2082/83?
These are the changes the Finance Act 2083 made, per IRD's Finance Act 2083 booklet. Other rows carried over from 2082/83.
- Insurance agents (natural persons): commission now has 20% TDS, and it is a final withholding.
- Ride-sharing: a new 1% final TDS on amounts the operator pays riders/drivers.
- Consumer committees (उपभोक्ता समिति): TDS on payments to them has been removed.
- Capital gains on listed shares (individual): up from 5% / 7.5% to 7.5% / 10%.
- Capital gains on land and houses (individual): up from 5% / 7.5% to 7.5% / 10%. Compulsory government acquisition is now 2.5%.
- Freelancers and creators: the 5% foreign-currency TDS (software, consulting, social-media content) is now explicitly a final withholding.
TDS revenue codes in Nepal (TDS type code / TDS code)
When you deposit TDS at a bank or through connectIPS, or enter it in the e-TDS system, you choose a revenue code (राजस्व शीर्षक). These are the IRD codes used for income tax and TDS:
| Revenue code | Revenue head (IRD) | Typically used for |
|---|---|---|
| 11111 | Tax on income of sole proprietorship and individuals | Income tax of individuals and sole proprietors |
| 11112 | Remuneration tax (पारिश्रमिक कर) | TDS on salary (above the SST band) |
| 11113 | Capital gains tax (individual) | Capital gains of individuals and sole proprietors (land, house, shares) |
| 11115 | Windfall gain tax (individual) | Lottery, prize, gift and similar to individuals |
| 11119 | Other tax on sole proprietorship income | Other individual business taxes |
| 11121 | Tax on profit: Government corporation | Income tax of government-owned entities |
| 11122 | Tax on profit: Public limited company | Income tax of public companies |
| 11123 | Tax on profit: Private limited company | Income tax of private companies |
| 11124 | Tax on profit: Other entities | Partnerships, cooperatives, trusts, foreign companies and others |
| 11125 | Capital gains tax: entity | Capital gains of entities |
| 11126 | Windfall gain tax: entity | Windfall gains of entities |
| 11129 | Other tax on entity income | Other entity taxes |
| 11131 | Tax on income from property, rent and lease | TDS on rent (house, land, vehicle and other leases) |
| 11132 | Tax on interest | TDS on interest |
| 11133 | Tax on dividend | TDS on dividends |
| 11134 | Tax on other investment income | Other investment-related income |
| 11139 | Tax on other income | Other income not listed above |
| 11211 | Social Security Tax on remuneration | 1% SST on salary (first slab) |
Codes 11120, 11130, 11200 and 11210 are header codes, and you can't deposit money under them.
Service fees, commissions and contract TDS: [In practice the TDS is booked against the withholdee's income-tax head: 11111 for individuals and sole proprietors, and 11122–11124 for entities by type.]
For the full revenue-code list, including VAT and excise codes, see Khatapana's guide to revised revenue codes for tax payment in Nepal.
When and how to deposit TDS (e-TDS)
- Deduct TDS when you make, or are liable to make, the payment. If you fail to deduct, the law treats it as deducted, and you are liable for it.
- Deposit the TDS amount under the right revenue code at a bank, or through electronic payment, within 25 days after the month ends.
- File the e-TDS return (the statement of tax deducted) on the IRD taxpayer portal within the same 25 days. Give each withholdee's PAN so the tax is credited to them.
- Withholdees can then see the TDS credited against their PAN and claim it in their return, unless it is a final withholding.
Final vs non-final TDS
Some TDS is final (अन्तिम कर कट्टी). The recipient doesn't add that income to their return. The main final-withholding payments are:
- dividends
- house rent paid to individuals not in business
- investment-insurance benefits
- unapproved retirement-fund benefits
- bank interest to individuals (6%)
- payments to non-residents
- retirement payments
- meeting allowances up to Rs 20,000 per meeting, and part-time teaching or exam work
- windfall gains
- mutual fund returns to individuals
- foreign-currency income of freelancers and creators (5%)
- insurance-agent commissions (20%)
- ride-sharing payments (1%)
- annual tax paid by hire-vehicle owners through the transport office
All other TDS is non-final: an advance against the recipient's annual tax.
FAQ
What is the TDS rate on service fees in Nepal 2083/84? 1.5% if the service provider is VAT-registered (or a VAT-exempt entity), and 15% otherwise.
What is the TDS rate on rent in Nepal? 10% on rent paid by a resident person or business. Rent paid to a VAT-registered vehicle-hire business is 1.5%. Individuals receiving house rent pay rent tax to the local government, so no TDS applies.
What is the TDS rate on contracts in Nepal? 1.5% on contract or agreement payments above Rs 50,000 to residents, and 5% to non-residents.
What is the revenue code for TDS on salary? 11112 (remuneration tax) for salary TDS, and 11211 for the 1% Social Security Tax portion.
What is the TDS revenue code for rent, interest and dividend? Rent 11131, interest 11132, dividend 11133.
When is TDS due in Nepal? Within 25 days after the end of the month in which you deducted it. Both the deposit and the e-TDS return are due by then.
- https://khatapana.com/blogs/118/revised-revenue-codes-for-tax-payment-in-nepal-that-every-tax-payer-should-know
- https://khatapana.com/blogs/499/tax-rate-in-nepal-208283-2025-complete-guide (salary slabs, SST)
- https://khatapana.com/salary-tax-calculator
- https://khatapana.com/taxes-and-accounting
- IRD, "आ.व.२०८३।०८४ लागि भुक्तानीमा कर कट्टी दर" (FY 2083/84 TDS rate notice, 22 Shrawan 2083): https://ird.gov.np/content/13607/s-o-2083-084-tax-cut-rate-for-payment/
- IRD, "राजस्व शीर्षक" (revenue code list, PDF): https://ird.gov.np/news/revenuecodes/ (PDF: https://giwmscdnone.gov.np/media/pdf_upload/1017295307_zpezela.pdf)
- IRD, Finance Act 2083 information booklet (TDS changes: insurance agents 20% final, ride-sharing 1%, consumer-committee TDS removed, capital gains rates): https://ird.gov.np/content/13632/economic-act--2083---information-booklet-on/
- IRD, Income Tax Act 2058 as amended by the Finance Act 2082, section 90 (25-day deposit and return deadline) and section 92 (final withholding payments): https://ird.gov.np/content/13405/income-tax-act--2058--as-amended-by/
- IRD, FY 2083/84 natural-person rate notice (salary slabs for section 87 TDS): https://ird.gov.np/content/13609/tax-rate-for-natural-persons-for-the/
Need help with tax & compliance?
PAN/VAT registration, monthly filings, e-TDS and audit support — handled by Khatapana experts.


Related Blogs
Subscribe to our newsletter
Get latest news and updates directly to your email.