NRB Introduces New Reforms Risking Nepal’s Grey List Status?
Khatapana
January 2, 2026 8 min read
 Reviewed by Kailash Panday, Chartered Accountant & Corporate Lawyer
NRB now allows blacklisted firms to receive investment and IT startups to expand abroad. Is this reform or risk? A deep dive into the Fifth Amendment to Foreign Investment and Foreign Loan Management Bylaws
On December 29, 2025, Nepal Rastra Bank amended the Foreign Investment and Foreign Loan Management Bylaws for the fifth time. At first glance, it looks like one of those technical updates that only lawyers and bankers are supposed to care about. But once you dig in, it becomes clear that this one reshapes some of the most sensitive parts of Nepal’s foreign investment framework.
For the first time, IT companies can invest abroad even if they haven’t built a consistent export track record over the past three years. The change that raised the most eyebrows, though, is: companies on the credit blacklist are no longer automatically barred from receiving foreign investment. At the same time, foreign investors can now repatriate their earnings directly through commercial banks, without making repeated trips to NRB for approvals. And share transfers involving foreign investment (once treated as a special, approval-heavy category) have been brought back into the standard process, with entire layers of paperwork stripped away.
To be clear, this isn't the NRB saying, “Do whatever you want.” Capital controls still exist, conditions still apply, and oversight has certainly not vanished. What has changed is that some long-standing bottlenecks have been removed, especially in places where they were slowing things down without really reducing risk.
Still, the changes raise some uncomfortable but necessary questions. Is it actually practical to allow foreign investment into companies that are already blacklisted? In a country that was put back on the Financial Action Task Force grey list just earlier this year, how will that be read internationally? And when NRB allows IT companies to take up to USD 20,000 abroad without a long export track record, how much discretion is really involved, and how tightly is that door being watched?
This article walks through these changes one by one. We look at what the rules were, what exactly NRB has changed, and what those changes mean in practice.
Let’s dive in.
1. $20K Foreign Exchange Route for IT Companies Without Consistent Exports
When NRB first permitted outward investment for IT companies in 2025, it did so cautiously. Eligibility was tied to a proven export track record. Only companies that had already earned foreign currency consistently over multiple years could qualify. From a risk-control perspective, this approach was understandable. From a market-entry perspective, it was deeply limiting.
The framework worked well for established exporters, but it excluded startups entirely. New and early-stage IT firms were expected to compete for foreign clients without the same credibility, structure, or legal presence as their more mature counterparts. In practice, this meant pitching to overseas customers without a local entity, without familiar contractual frameworks, and often without the commercial comfort that clients expect when engaging a service provider.
Predictably, foreign clients tended to prefer companies that already operated within their jurisdiction. That made it harder for startups to win contracts, harder to maintain consistent exports, and nearly impossible to qualify for outward investment approval under NRB’s original criteria. The result was a structural deadlock: companies needed a foreign presence to build exports, but needed exports to qualify for a foreign presence.
The USD 20,000 Facility: A Targeted Course Correction
The introduction of the USD 20,000 outward investment facility directly addresses this deadlock in section 9(4)(A) of the amended Bylaws. Rather than treating export history as a prerequisite, NRB created a limited, controlled allowance that reflects how early-stage international expansion actually happens.
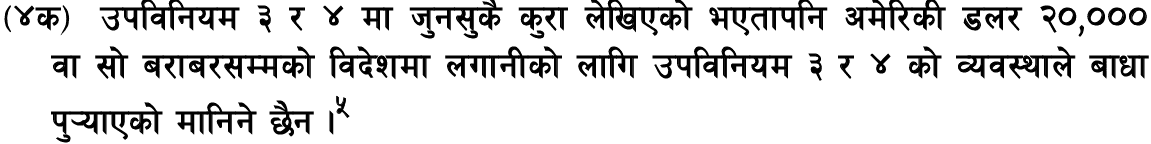
Under this facility, eligible IT companies can invest up to USD 20,000, or an equivalent amount in convertible currency for the purpose of establishing a basic foreign presence. The desired investment amount, however, should not exceed the total paid-up capital of the company.
The most consequential change here is not the amount itself, but the removal of the prior export earnings requirement for this specific tier. For first-time founders, bootstrapped startups, and service exporters still in the early stages of building international revenue, this removes a long-standing structural barrier and allows them to compete on more equal footing.
Why This Evolution Matters
Taken together, these changes represent a shift in posture rather than a policy reversal. NRB has moved from near-prohibition to conditional permission by opening a controlled path for IT companies to establish a presence abroad without dismantling the broader foreign exchange safeguards.
Understanding this evolution is critical, because the sections that follow do not deal only with how money can go out, but also with how it comes back, how investments are exited, and how companies (both growing and distressed) fit into this recalibrated framework.
2. Automatic Repatriation via Banks—No NRB Visits
For all the attention given to outward investment, one of the most consequential changes in the Fifth Amendment sits on the other side of the transaction: how money comes back. While this reform has attracted less public discussion, its impact on investor confidence and deal structuring is arguably even larger.
What the Old Repatriation Process Looked Like
Under the earlier framework, repatriating returns on foreign investment was technically allowed but procedurally heavy. Every kind of repatriation, whether it involved dividends, royalties, or proceeds from a share sale, required case-by-case approval from Nepal Rastra Bank, typically routed through the Foreign Exchange Facilitation Unit.
In practice, this meant physical file movement between banks and NRB, multiple rounds of document scrutiny, and no predictable timeline for approval
Even when the underlying transaction was clean, taxed, and compliant, investors and companies were left dealing with uncertainty. For foreign investors in particular, this approval-heavy exit process was often flagged as a risk, not because repatriation was prohibited, but because it was slow, opaque, and difficult to plan around.
Over time, this friction affected more than just exits. It influenced how deals were priced, how shareholder agreements were drafted, and in some cases, whether investors chose to enter the Nepali market at all.
What Has Changed Regarding Repatriations
Section 6 of the Fifth Amendment to the Foreign Investment and Foreign Loan Management Bylaws fundamentally restructures this process by shifting operational authority from NRB to Class ‘A’ commercial banks. Instead of routing every repatriation request through NRB, investors can now directly approach their bank, which is empowered to process the transaction after verifying the required documentation.
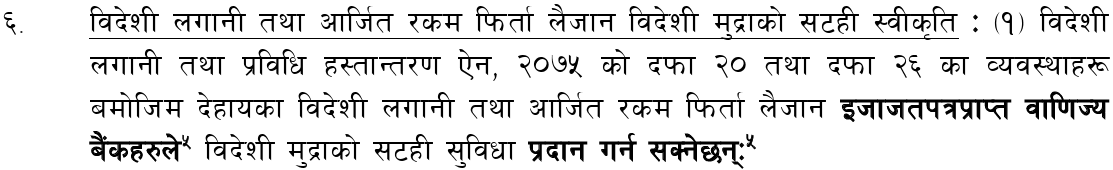
Hence, NRB no longer needs to issue a specific approval for each repatriation. The role of verification has been delegated to banks, which assess the company’s compliance and processes the foreign exchange transfer. The result is a faster, more predictable process that aligns better with commercial timelines and investor expectations.
Importantly, this does not mean NRB has stepped away from oversight altogether. The control has shifted from transaction-by-transaction approval to a framework-based, bank-led compliance model. Oversight remains, but it operates through delegation rather than micromanagement.
3. Blacklist Listed Entities Allowed to Bring in Foreign Investment
Among the Fifth Amendment’s changes, the treatment of blacklist-listed entities is the most delicate and the most revealing. Not because it announces a bold new permission, but because of how quietly and narrowly it has been implemented.
Importantly, this reform does not appear through a new standalone clause declaring blacklisted companies eligible for foreign investment. Instead, Nepal Rastra Bank has engineered the change through revisions to Annex 2 and Annex 3, by altering the documentary conditions attached to foreign investment approvals.
What Exactly Changed, And Where
Previously, the process was absolute. Among the mandatory documents required for foreign investment, companies had to submit a non-blacklist certification from the Credit Information Bureau (CIB). If the company appeared on the blacklist, the application effectively stopped there. No discretion, no nuance, no further processing.
Under the Fifth Amendment, this mechanism has been recalibrated.
Through revisions to the following:
- Annex 2 (“written information to be submitted to NRB before bringing in foreign currency”), and
- Annex 3 (“documents to be verified by banks and financial institutions”),
NRB has replaced the automatic prohibition with a self-declaration framework.
Under the amended checklist, If the company is not blacklisted, it submits the usual CIB clearance.
If the company is blacklisted, the foreign investor (or lender) must:
- acknowledge awareness of the blacklist status,
- submit documentary evidence of the blacklist report, and
- formally declare that they understand and accept that repatriation of investment or loan repayment is not permitted until the company exits the blacklist, as per the relevant annexes.
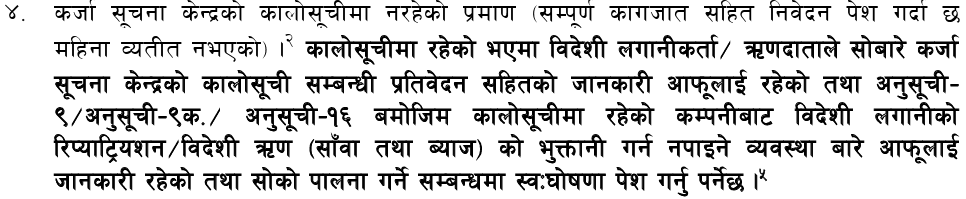
In other words, blacklist status no longer blocks entry at the gate, but it does lock the exit.
The Logic Behind This Reform
From a policy standpoint, the logic is quite defensible. Blacklist status often reflects liquidity stress or loan default, not necessarily fraud or criminality. By blocking all capital (including equity,) the earlier framework often converted financial distress into permanent paralysis. Companies that needed fresh capital to repay domestic obligations and stabilize operations were denied exactly the instrument that could enable recovery. So, by allowing foreign equity to enter (while continuing to restrict repatriation) the revised framework tries to strike a balance. Capital can come in to fix the problem, but it cannot leave until the problem is resolved.
The Other Side of the Coin: An Uncomfortable Question
But this is where the duality of the reform becomes impossible to ignore.
Are we so constrained for foreign capital that we are now willing to accept it even into companies that have already failed domestic credit discipline?
Yes, repatriation is barred until the company exits the blacklist, and that is a meaningful safeguard. But it raises a more practical question: who actually invests under these conditions?
In reality, arm’s-length, commercially neutral foreign investors rarely invest in companies that are so financially distressed that they are blacklisted, which is why source-of-funds scrutiny, ownership transparency, and end-use monitoring become exponentially more important.
The concern at hand is amplified further by context. Nepal was placed back on the grey list of the Financial Action Task Force in February 2025. Changes like this can further aggravate our standing, and before we know it, the nation could find itself placed on the blacklist. While this may sound extreme, it is not entirely impossible either.
On Audit Reports and NRB’s Role
If you noticed it, NRB has removed its own requirement to directly receive and review audit reports in certain foreign investment and repatriation processes.
On its own, this change is less alarming than it sounds.
Audit obligations have not disappeared. Companies do not get to skip audits altogether. Other regulators and authorities; including tax bodies and sectoral regulators such as the Department of Industry, continue to require audited financials at different stages. What has changed is institutional sequencing, not substantive oversight.
NRB has stepped back from being a universal checkpoint, but the information itself continues to circulate within the regulatory system.
4. Simplified Share Transfer Recording
One of the most consequential operational changes in the Fifth Amendment does not announce itself loudly. There is no new facility, no headline-grabbing limit, and no obvious policy shift. Instead, it appears through something far more telling: the complete removal of an entire approval architecture related to share-ownership-change–based foreign investment.
What the Previous Process Looked Like
Previously, foreign investment coming into Nepal through a change in share ownership; as opposed to fresh issuance, was treated as a special, high-scrutiny category. The framework went out of its way to define what constituted “foreign investment through share ownership change” in section 2(14)(A), carved it out as a separate concept in section, and then subjected it to a distinct approval process at NRB level.
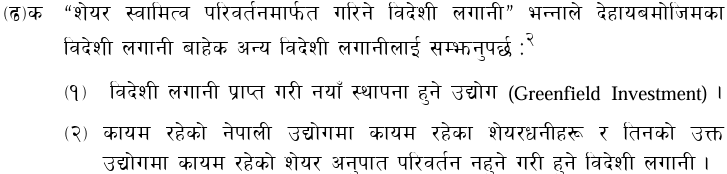
That architecture has now been dismantled.
What has Changed Regarding Share Transfer Recording
At the definitional level itself, the Fifth Amendment removes the earlier definition of “foreign investment through share ownership change” from the regulation.

In practical terms, this means such transactions are no longer treated as a separate species of foreign investment requiring special handling. They are absorbed into the general foreign investment framework instead of being isolated as an exception.
This definitional cleanup is reinforced by a more direct procedural change. The requirement to obtain prior approval from NRB, along with submission of a dedicated document set under Annex 4 for remitting or bringing in foreign currency arising from share-ownership-change–based investment has been removed entirely. Annex 4 itself, which once listed the documents required specifically for such approvals, has been deleted.
Equally important is what was removed from the operative provisions. The earlier rule that explicitly mandated NRB’s prior approval for foreign investment resulting from a change in share ownership, along with a prescribed 15-working-day decision timeline has also been repealed. With this deletion, the legal basis for mandatory NRB-level clearance in such cases no longer exists.
This does not mean share transfers are unregulated. Commercial banks still verify the legitimacy of the transaction, the source of funds, and compliance with applicable investment and company law requirements. What has changed is the removal of structural duplication, where even clean, intra-investor or secondary transactions were being slowed down by an additional approval layer that added little substantive oversight.
Final Thoughts
If there’s one takeaway from these changes, it’s this: NRB hasn’t exactly thrown the doors open, but it has definitely stopped blocking the hallway.
Across outward investment, repatriation, blacklist treatment, and share transfer recording, the pattern is consistent. Friction has been reduced where it made little sense. Bottlenecks have been removed where they added delay but not discipline. And responsibility has shifted away from case-by-case approvals toward clearer rules and bank-led verification.
That doesn’t mean the system is suddenly permissive. What’s changed is usability.
For startups, the path to international markets is no longer structurally blocked.
For investors, exits are more predictable.
For share transfers, routine transactions no longer require unnecessary escalation.
Whether this recalibration succeeds will depend less on the wording of the bylaws and more on how consistently they’re applied. Coordination between NRB, banks, and other regulators now matters more than ever.
Starting a business in Nepal?
Register your company online — name reservation, MOA/AOA, PAN/VAT and OCR filings, all in one place.

Related Blogs
Subscribe to our newsletter
Get latest news and updates directly to your email.