Tax Rate in Nepal 2083/84: Income Tax Slabs, SST & Rates
Khatapana
June 4, 2025 8 min read
 Reviewed by Kailash Panday, Chartered Accountant & Corporate Lawyer
Quick answer
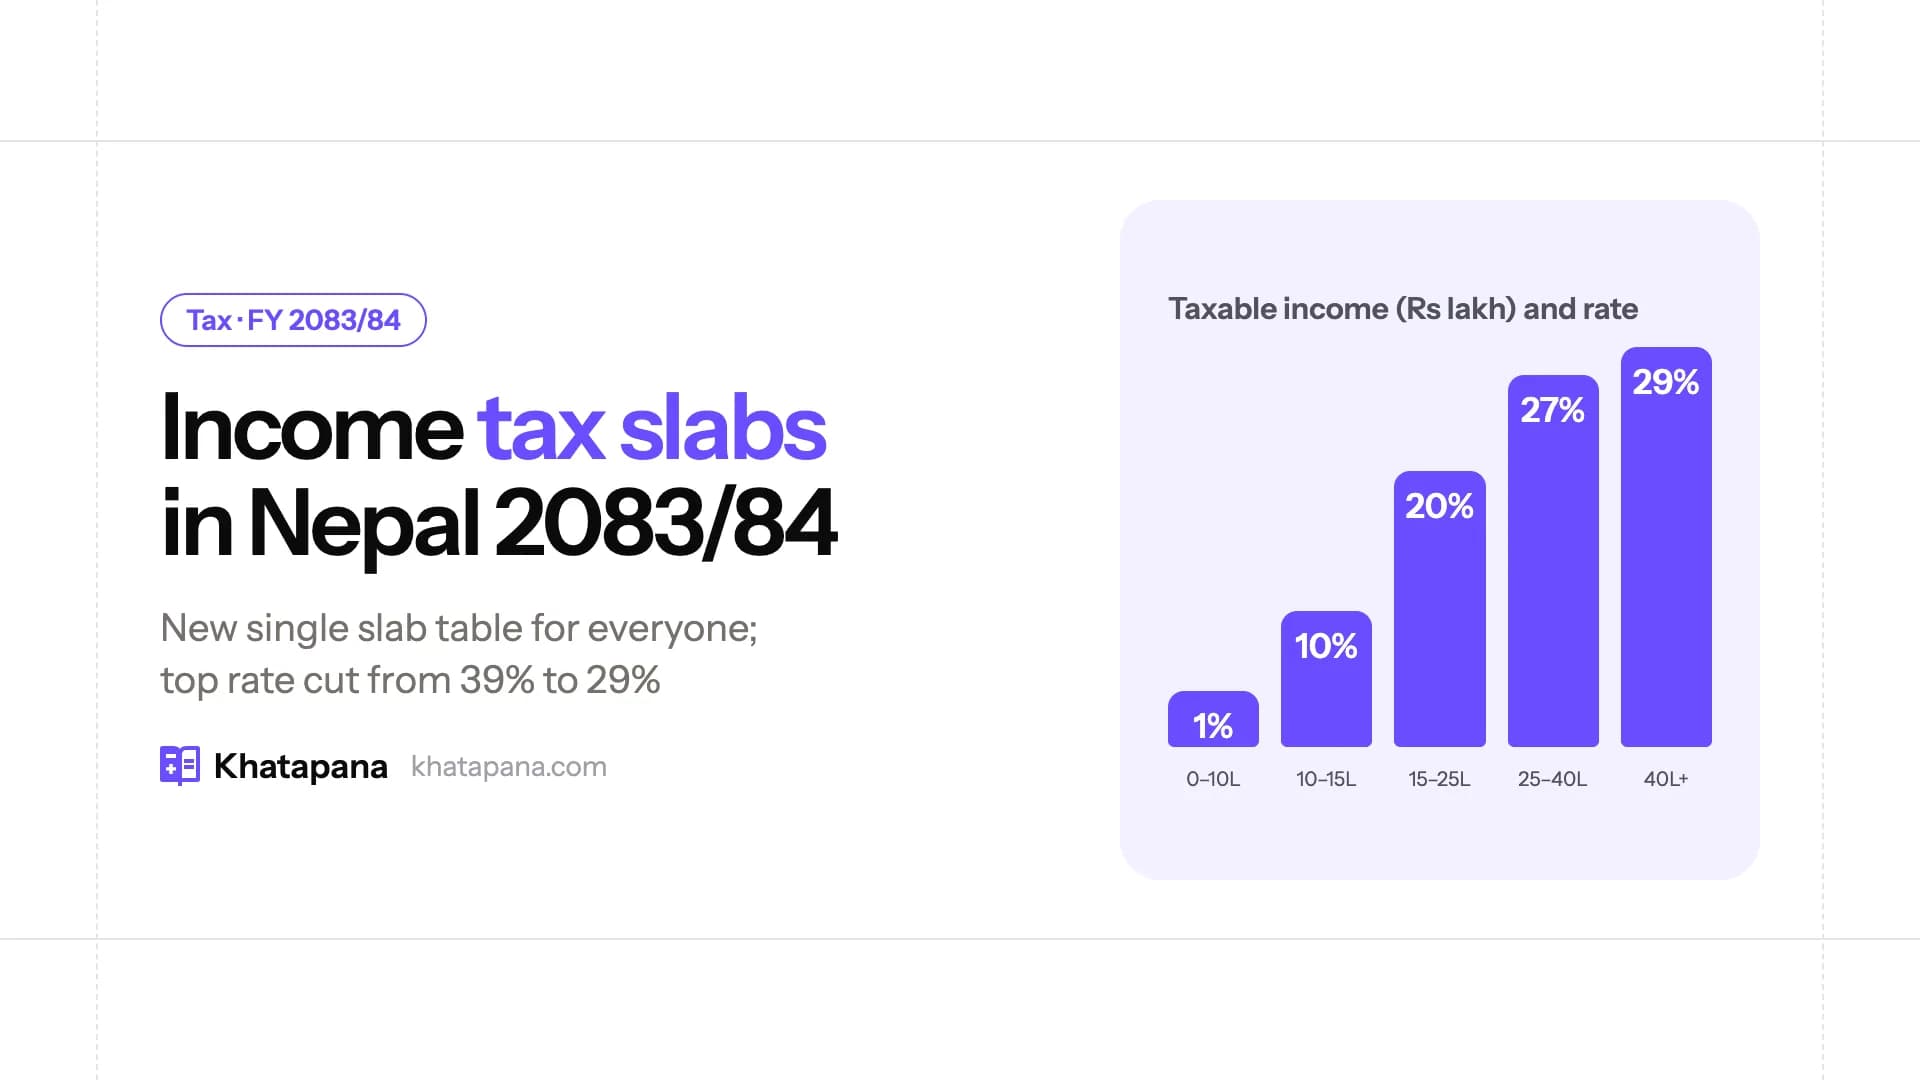
For FY 2083/84, individuals pay 1% on the first Rs 10 lakh, 10% up to Rs 15 lakh, 20% up to Rs 25 lakh, 27% up to Rs 40 lakh and 29% above that, with the same slabs for single and married taxpayers. The 1% is Social Security Tax and is waived for SSF contributors. Companies pay 25%, or 30% for banks and telecoms.
- New 2083/84 slabs: 1% to Rs 10 lakh, then 10%, 20%, 27% and a 29% top rate (was 39%).
- No separate couple table from 2083/84; 2082/83 used Rs 5 lakh (single) and Rs 6 lakh (couple) first slabs.
- Deductions: retirement up to Rs 5 lakh or one-third of income, life insurance Rs 40,000, health insurance Rs 20,000.
For FY 2083/84 (from Shrawan 1, 2083 / mid-July 2026), resident individuals pay income tax on these slabs:
- 1% on the first Rs 10 lakh
- 10% on Rs 10–15 lakh
- 20% on Rs 15–25 lakh
- 27% on Rs 25–40 lakh
- 29% above Rs 40 lakh
The same table now applies to single and married taxpayers. Companies pay 25%, and banks, telecoms and some other sectors pay 30%. The 1% on the first slab is Social Security Tax (SST). It is waived if you contribute to the Social Security Fund (SSF).
Source: Inland Revenue Department notice "आ.व. २०८३/०८४ लागि करको दर प्राकृतिक व्यक्तिको लागि" (22 Shrawan 2083) and the Finance Act 2083.
What changed (2082/83 → 2083/84)
| FY 2082/83 (previous) | FY 2083/84 (current) | |
|---|---|---|
| First (1%) slab | Rs 5 lakh single / Rs 6 lakh couple | Rs 10 lakh, same for single and couple |
| Highest rate | 39% (above Rs 50 lakh) | 29% (above Rs 40 lakh) |
| Separate couple table | Yes | No. One table applies to everyone |
| Building insurance deduction | Up to Rs 5,000 | Up to Rs 10,000 |
| Children's tuition fee deduction | — | New: 25% of fees or Rs 25,000, whichever is lower |
| Capital gains, land/house (individual) | 5% (≥5 yrs) / 7.5% (<5 yrs) | 7.5% / 10% |
| Capital gains, listed shares (individual) | 5% (>365 days) / 7.5% | 7.5% / 10% |
The FY 2082/83 budget made no change to personal slabs or the general corporate rate.
Income tax slab in Nepal 2083/84 (individual and couple)
This is the official IRD table for resident natural persons in income year 2083/84. The "single" and "couple" columns are identical.
| Taxable income (Rs per year) | Rate | Tax on this band | Cumulative tax at top of band |
|---|---|---|---|
| Up to 10,00,000 | 1% (SST) | 10,000 | 10,000 |
| 10,00,001 – 15,00,000 | 10% | 50,000 | 60,000 |
| 15,00,001 – 25,00,000 | 20% | 2,00,000 | 2,60,000 |
| 25,00,001 – 40,00,000 | 27% | 4,05,000 | 6,65,000 |
| Above 40,00,000 | 29% (27% + 2 points) | — | 6,65,000 + 29% of the excess |
IRD's own example: a person with Rs 60 lakh taxable income pays Rs 12,45,000. That is 10,000 + 50,000 + 2,00,000 + 4,05,000 + 5,80,000.
No 1% on the first slab for:
- sole proprietorship (एकलौटी फर्म) taxpayers
- pension income
- people contributing to a pension fund (निवृत्तिभरण कोष) or the contribution-based Social Security Fund
Tax slab in Nepal 2082/83 (previous year, for 2082/83 returns)
This is the income year 2082/83 table (Income Tax Act Schedule 1, as amended by the Finance Act 2082). Use it only for income earned between mid-July 2025 and mid-July 2026.
Single (individual):
| Taxable income (Rs) | Rate | Cumulative tax at top of band |
|---|---|---|
| Up to 5,00,000 | 1% (SST) | 5,000 |
| 5,00,001 – 7,00,000 | 10% | 25,000 |
| 7,00,001 – 10,00,000 | 20% | 85,000 |
| 10,00,001 – 20,00,000 | 30% | 3,85,000 |
| 20,00,001 – 50,00,000 | 36% (30% + 20% of 30%) | 14,65,000 |
| Above 50,00,000 | 39% (30% + 30% of 30%) | — |
Couple (married, if elected under section 50):
| Taxable income (Rs) | Rate | Cumulative tax at top of band |
|---|---|---|
| Up to 6,00,000 | 1% (SST) | 6,000 |
| 6,00,001 – 8,00,000 | 10% | 26,000 |
| 8,00,001 – 11,00,000 | 20% | 86,000 |
| 11,00,001 – 20,00,000 | 30% | 3,56,000 |
| 20,00,001 – 50,00,000 | 36% | 14,36,000 |
| Above 50,00,000 | 39% | — |
Tax slab for married in Nepal
From FY 2083/84 there is no separate married-couple slab. The Finance Act 2083 merged the two tables. IRD's 2083/84 notice lists the same bands and the same tax for "एकल" (single) and "दम्पती" (couple). Up to FY 2082/83, a couple who elected joint treatment got a first slab of Rs 6 lakh instead of Rs 5 lakh. The couple's 30% band was also Rs 9 lakh instead of Rs 10 lakh. So a couple at Rs 60 lakh paid Rs 18,26,000, against Rs 18,55,000 for a single person.
SST in Nepal (Social Security Tax)
- What it is: The 1% charged on the first slab of employment (salary) income. It is Rs 10 lakh in 2083/84 and was Rs 5/6 lakh in 2082/83. Employers deposit it under revenue code 11211, separately from the rest of salary tax (code 11112).
- Who doesn't pay it:
- employees contributing to the contribution-based Social Security Fund (SSF)
- contributors to the pension fund (निवृत्तिभरण कोष)
- pension income
- sole proprietorship firms
- CIT or EPF alone doesn't waive SST. Only SSF or pension-fund contributions are listed in the exemption.
Salary tax in Nepal (with example)
Your employer deducts salary tax (TDS) every month. It takes your estimated annual taxable salary, applies the slab table, and divides the result by the months remaining. The full-year calculation works like this:
- Annual taxable salary = gross salary + taxable allowances and bonuses − allowed deductions. Allowed deductions are retirement contributions, insurance premiums and the remote allowance (see the next section).
- Apply the 2083/84 slabs.
- Subtract rebates. These are the 10% female rebate and the medical tax credit.
Example (FY 2083/84): Gross salary Rs 18,00,000 a year (Rs 1,50,000 a month). You put Rs 3,00,000 into CIT, and pay Rs 40,000 life insurance and Rs 20,000 health insurance premiums. You are not in SSF.
- Taxable income = 18,00,000 − 3,00,000 − 40,000 − 20,000 = Rs 14,40,000.
- Tax = 10,000 (1% on 10 lakh) + 44,000 (10% on 4.4 lakh) = Rs 54,000 a year (Rs 4,500 a month).
- If the employee is a woman with only salary income: 10% rebate → Rs 48,600.
- The same Rs 14,40,000 in FY 2082/83 (single) was taxed at Rs 2,17,000. That is 5,000 + 20,000 + 60,000 + 30% of 4,40,000 (1,32,000).
Try it yourself with the free Khatapana salary tax calculator. [Publish this link only once /salary-tax-calculator is live; until then link /blogs/318.]
Tax deduction in Nepal (what you can subtract, FY 2083/84)
| Deduction / relief | Limit (FY 2083/84) | Note |
|---|---|---|
| Retirement contributions (SSF, EPF, CIT, approved pension fund) | Lower of Rs 5,00,000 or one-third of assessable income | Combined limit for all approved funds |
| Life (investment) insurance premium | Lower of premium paid or Rs 40,000 | Unchanged |
| Health insurance premium (resident insurer) | Lower of premium paid or Rs 20,000 | Unchanged |
| Private building insurance (own house, resident insurer) | Lower of premium paid or Rs 10,000 | Up from Rs 5,000 |
| Children's tuition fees paid to a resident school/college | Lower of 25% of fees paid or Rs 25,000 | New in 2083/84 |
| Remote-area allowance | Category A Rs 50,000 · B Rs 40,000 · C Rs 30,000 · D Rs 20,000 · E Rs 10,000 | Deducted from taxable income |
| Pension income | Extra deduction of 25% of the first-slab amount (subject to the prescribed cap) | |
| Person with disability | Extra deduction of 50% of the first-slab amount | |
| Female with only salary income | 10% rebate on tax payable | Rebate on tax, not a deduction from income |
| Medical expenses (approved) | Tax credit of 15% of bills or Rs 750, whichever is lower | Credit against tax |
Tax rate for proprietorship firm in Nepal
A sole proprietorship (एकलौटी फर्म) is taxed as its owner, a natural person, on the same 2083/84 slab table. The difference is that the 1% on the first slab doesn't apply. So the first Rs 10 lakh of taxable business profit carries no income tax. After that it is 10% / 20% / 27% / 29%.
| Taxable profit (Rs) | Proprietorship rate, FY 2083/84 |
|---|---|
| Up to 10,00,000 | 0% |
| 10,00,001 – 15,00,000 | 10% |
| 15,00,001 – 25,00,000 | 20% |
| 25,00,001 – 40,00,000 | 27% |
| Above 40,00,000 | 29% |
Very small proprietors can pay a fixed presumptive tax instead (next section). Concessions for special industries, IT and export income still exist for individuals. They are worded as "where tax is levied at 30%", and the 2083/84 table no longer has a 30% band.
Presumptive tax in Nepal (small businesses)
Presumptive (fixed) tax, D-01 return: for resident individuals with taxable business income up to Rs 3 lakh and turnover up to Rs 30 lakh.
| Business location | Annual tax, FY 2083/84 |
|---|---|
| Metropolitan / sub-metropolitan city | Rs 7,500 |
| Municipality | Rs 4,000 |
| Other areas (rural municipality) | Rs 2,500 |
Turnover-based tax, D-02 return: for resident individuals with only Nepal-source business income, taxable income up to Rs 10 lakh and turnover above Rs 30 lakh up to Rs 1 crore. It isn't available for professional or expert services such as doctors and engineers. You pay the presumptive amount above, plus:
| Business type | Turnover Rs 30–50 lakh | Turnover Rs 50 lakh–1 crore |
|---|---|---|
| Gas, cigarettes and similar (margin up to 3%) | 0.25% | 0.30% |
| Other trading | 1% | 0.8% |
| Services | 2% | 2% |
Turnover tax is paid in two instalments: by Poush-end, and by Asar-end.
Example: A clothing shop in Kathmandu with Rs 60 lakh turnover pays:
- Rs 7,500 presumptive tax
- 1% of Rs 20 lakh (Rs 20,000)
- 0.8% of Rs 10 lakh (Rs 8,000)
- Total: Rs 35,500
The provision granting zero-transaction/dormant businesses relief/exemption from paying fixed annual presumptive taxes was enacted in the Finance Act 2082 and remains in effect as part of the principal Income Tax Act procedural rules, even though it isn't explicitly re-printed in IRD's annual rate notice.
Corporate tax rate in Nepal (FY 2083/84)
| Entity / business | Rate |
|---|---|
| General companies and entities | 25% |
| Banks, financial institutions, general insurance, financial-transaction entities, telecom and internet, money transfer, capital-market, securities and merchant banking, commodity futures, brokers, tobacco/alcohol/beer businesses, petroleum (Nepal Petroleum Act) | 30% |
| Cooperatives (non-exempt transactions): municipality / sub-metro / metro | 5% / 7% / 10% |
| Savings-and-credit cooperatives: municipality / sub-metro / metro | 10% / 15% / 20% |
| Schools and colleges run under a public trust | 20% |
| Repatriated income of a non-resident's permanent establishment | 5% |
| Non-resident individual (taxable income) | 25% |
Key incentives (Income Tax Act section 11, per IRD's 2083/84 list):
- Special industries, hotels/resorts and IT industries: 20% off the tax for entities, so 25% becomes an effective 20%. More relief applies for 100+, 300+, 500+ and 1,000+ Nepali employees (pay 90% / 80% / 75% / 70% of the tax).
- Special industries in least-developed / undeveloped / underdeveloped areas: pay only 10% / 20% / 30% of the tax for 10 years from starting operations.
- Startups: innovation-based startups designated by IRD with turnover up to Rs 10 crore pay no tax for 5 years. (Why that relief is thinner than it looks.)
- Export income: 20% off the tax for entities.
- IT-based services exported for foreign currency (BPO, software programming, cloud computing): 50% off the tax on that income until FY 2084/85.
- Special Economic Zones: no tax for 10 years in Himalayan and designated hill districts (5 years elsewhere), then 50% off.
Tax rate in Nepal for freelancers (5% final)
A resident individual not running a registered business pays a 5% final tax on income received in foreign currency for:
- software or similar electronic services provided abroad
- consulting services provided personally abroad
- uploading audio-visual content to social media
The bank or money-transfer company deducts the 5% when it pays you. Because it is a final withholding, you don't add this income to a return. Make sure your PAN is linked to the receiving account.
Capital gains tax for individuals (FY 2083/84)
| Asset | Holding period | Rate |
|---|---|---|
| Land / house (non-business) | 5 years or more | 7.5% |
| Land / house (non-business) | Less than 5 years | 10% |
| Land acquired by the Government (involuntary) | — | 2.5% |
| Listed shares | More than 365 days | 7.5% |
| Listed shares | 365 days or less | 10% |
Frequently asked questions
What is the income tax rate in Nepal 2082/83? For FY 2082/83, singles paid 1% on the first Rs 5 lakh, then 10% / 20% / 30% / 36% / 39%. Couples got a Rs 6 lakh first slab. From FY 2083/84 the slabs are 1% up to Rs 10 lakh, then 10% / 20% / 27% / 29%, the same for everyone.
Is income up to Rs 10 lakh tax-free in Nepal now? Not quite. Up to Rs 10 lakh of salary income carries the 1% Social Security Tax (Rs 10,000 a year at most). It drops to zero if you contribute to SSF or a pension fund, if it's pension income, or if you're a sole proprietorship.
Is there a different tax slab for married couples in Nepal? Not from FY 2083/84. IRD's table shows identical slabs for single and couple taxpayers. The separate couple table (first slab Rs 6 lakh) applied up to FY 2082/83.
How much tax will I pay on a salary of Rs 1 lakh a month? Rs 12 lakh a year, with no deductions and not in SSF: Rs 10,000 + 10% of Rs 2 lakh = Rs 30,000 a year (Rs 2,500 a month) in FY 2083/84. Under the 2082/83 single slabs it was Rs 1,45,000. Deductions such as CIT and insurance reduce this further.
What is the corporate tax rate in Nepal? 25% for most companies, and 30% for banks, financial institutions, telecoms, tobacco, alcohol and petroleum businesses. Special industries, exporters and startups get concessions.
How much is presumptive tax in Nepal? Rs 7,500 in metropolitan or sub-metropolitan cities, Rs 4,000 in municipalities, and Rs 2,500 elsewhere. It applies to individuals with turnover up to Rs 30 lakh and income up to Rs 3 lakh.
- /blogs/318 (salary tax calculator article) and /salary-tax-calculator (once live)
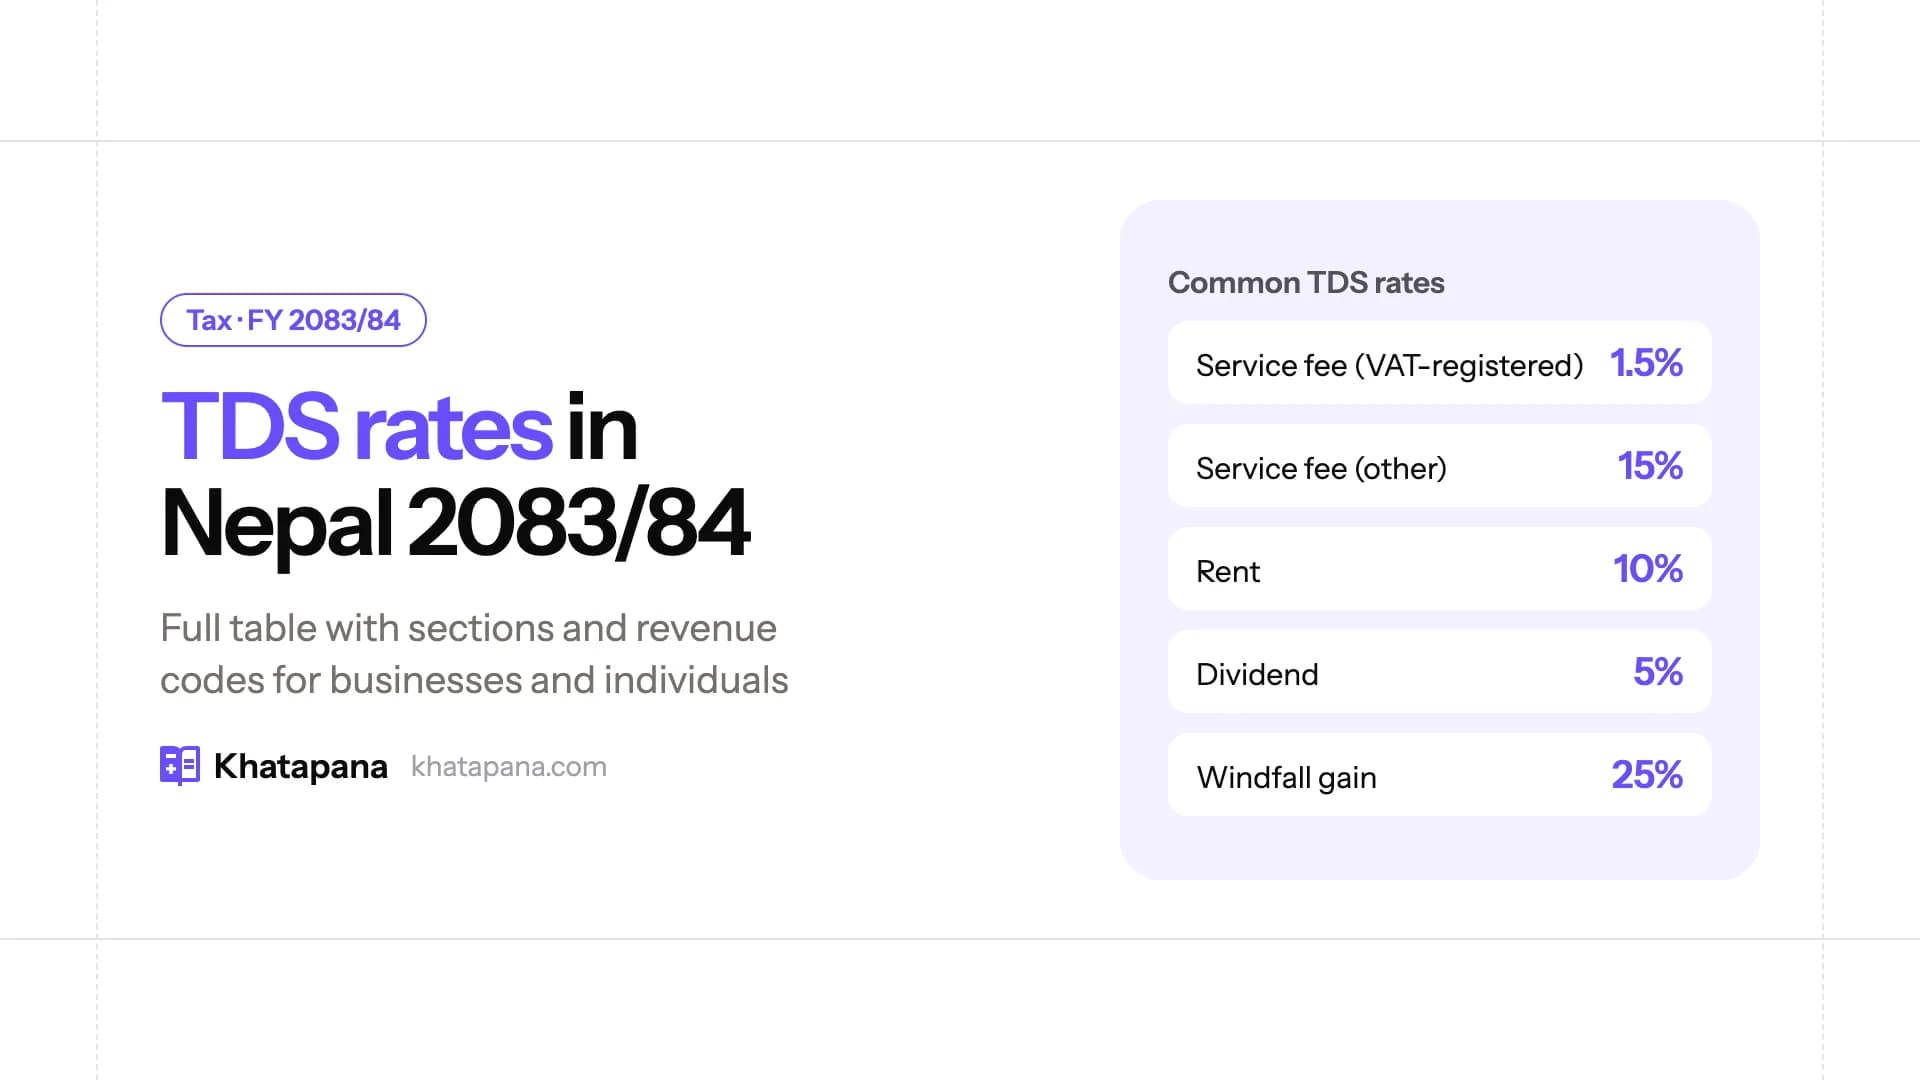
- New TDS article:
new-tds-rates-nepal.md(slug suggested there) - https://khatapana.com/blogs/118/revised-revenue-codes-for-tax-payment-in-nepal-that-every-tax-payer-should-know (SST / remuneration revenue codes)
- https://www.khatapana.com/blogs/452/0-tax-rate-in-nepal-for-startups-real-relief-or-ju
- https://khatapana.com/blogs/34/simplified-method-of-taxation-for-small-businesses
- /taxes-and-accounting (service CTA)
Sources
- IRD, "आ.व.२०८३।०८४ लागि करको दर प्राकृतिक व्यक्तिको लागि" (22 Shrawan 2083). Covers the slab table, single = couple, SST exemptions, deductions, remote categories, female rebate, medical credit, presumptive and turnover tax, capital gains and the 5% foreign-currency rule: https://ird.gov.np/content/13609/tax-rate-for-natural-persons-for-the/
- IRD, "आ.व.२०८३।०८४ लागि निकायको लागि आयकरको दर" (entity rates): https://ird.gov.np/content/13608/income-tax-rate-for-the-entity-for/
- IRD, "आ.व.२०८३।०८४ लागिका लागि दफा ११ बमोजिमका छुट तथा सुविधाहरू" (section 11 incentives): https://ird.gov.np/content/13606/notice111/
- IRD, Finance Act 2083 (gazette date 2083/03/30): https://ird.gov.np/content/13566/economic-act--2083--date-of-publication-in/
- IRD, "आर्थिक ऐन, २०८३: कर छुट, सहुलियत र अन्य व्यवस्था सम्बन्धी जानकारीमूलक पुस्तिका" (22 Bhadra 2083; revised edition 26 Asoj 2083). Confirms the slab change, the 39%→29% top rate, building insurance at Rs 10,000, tuition fee at 25%/Rs 25,000, and the capital gains increases: https://ird.gov.np/content/13632/economic-act--2083---information-booklet-on/ and https://ird.gov.np/content/13670/economic-act--2083-information-manual-on-tax/
- Ministry of Finance, Finance Bill 2083 (text of the Schedule 1 amendment: single table for "individual or couple", subsection (2) deleted): https://mof.gov.np/content/1742/economic-bill--2083/
- IRD, Income Tax Act 2058 as amended by the Finance Act 2082 (FY 2082/83 single and couple tables, SST proviso, deductions): https://ird.gov.np/content/13405/income-tax-act--2058--as-amended-by/
- IRD revenue codes (11112 remuneration tax, 11211 social security tax): https://ird.gov.np/news/revenuecodes/
- The Kathmandu Post, budget FY 2026/27 report (29 May 2026). Note: it describes the Rs 10 lakh band as "exempt", but the law applies 1% SST: https://kathmandupost.com/money/2026/05/29/finance-minister-wagle-unveils-budget-for-fiscal-year-2026-27-announces-tax-relief-and-ministry-cuts
Need help with tax & compliance?
PAN/VAT registration, monthly filings, e-TDS and audit support — handled by Khatapana experts.

Related Blogs
Subscribe to our newsletter
Get latest news and updates directly to your email.